Law firm-owned obligations
No artificial transfers of debt and no assumption that BK Aftermath is the creditor.
We are developing a specialized process that helps bankruptcy law firms prepare and administer truthful reporting of eligible attorney-fee payment agreements—without changing who owns the debt.
Explore Our Framework →BK Aftermath is designed as a contracted reporting administrator. The participating law firm owns the receivable, manages its client relationship, and maintains authoritative contract and payment records. BK Aftermath's proposed services focus on reviewing, validating, processing, and supporting the reporting workflow under an appropriate bureau-approved arrangement.
No artificial transfers of debt and no assumption that BK Aftermath is the creditor.
Actual contractual terms, payments, reversals, balances and corrections—not manufactured tradelines.
Bankruptcy timing, enforceability and bureau acceptance must be evaluated before furnishing.
Before any account enters an approved furnishing workflow, we expect documented source agreements, transaction-level ledger reconciliation, exception handling and appropriately controlled access.
Account statuses are determined by actual events. The program cannot promise positive reporting only or guarantee any credit-score improvement.
Our intended workflow combines law firm onboarding, bankruptcy-specific account screening, accurate file preparation and ongoing monitoring. Actual submission requires the correct furnisher identity, account category and each bureau's acceptance.
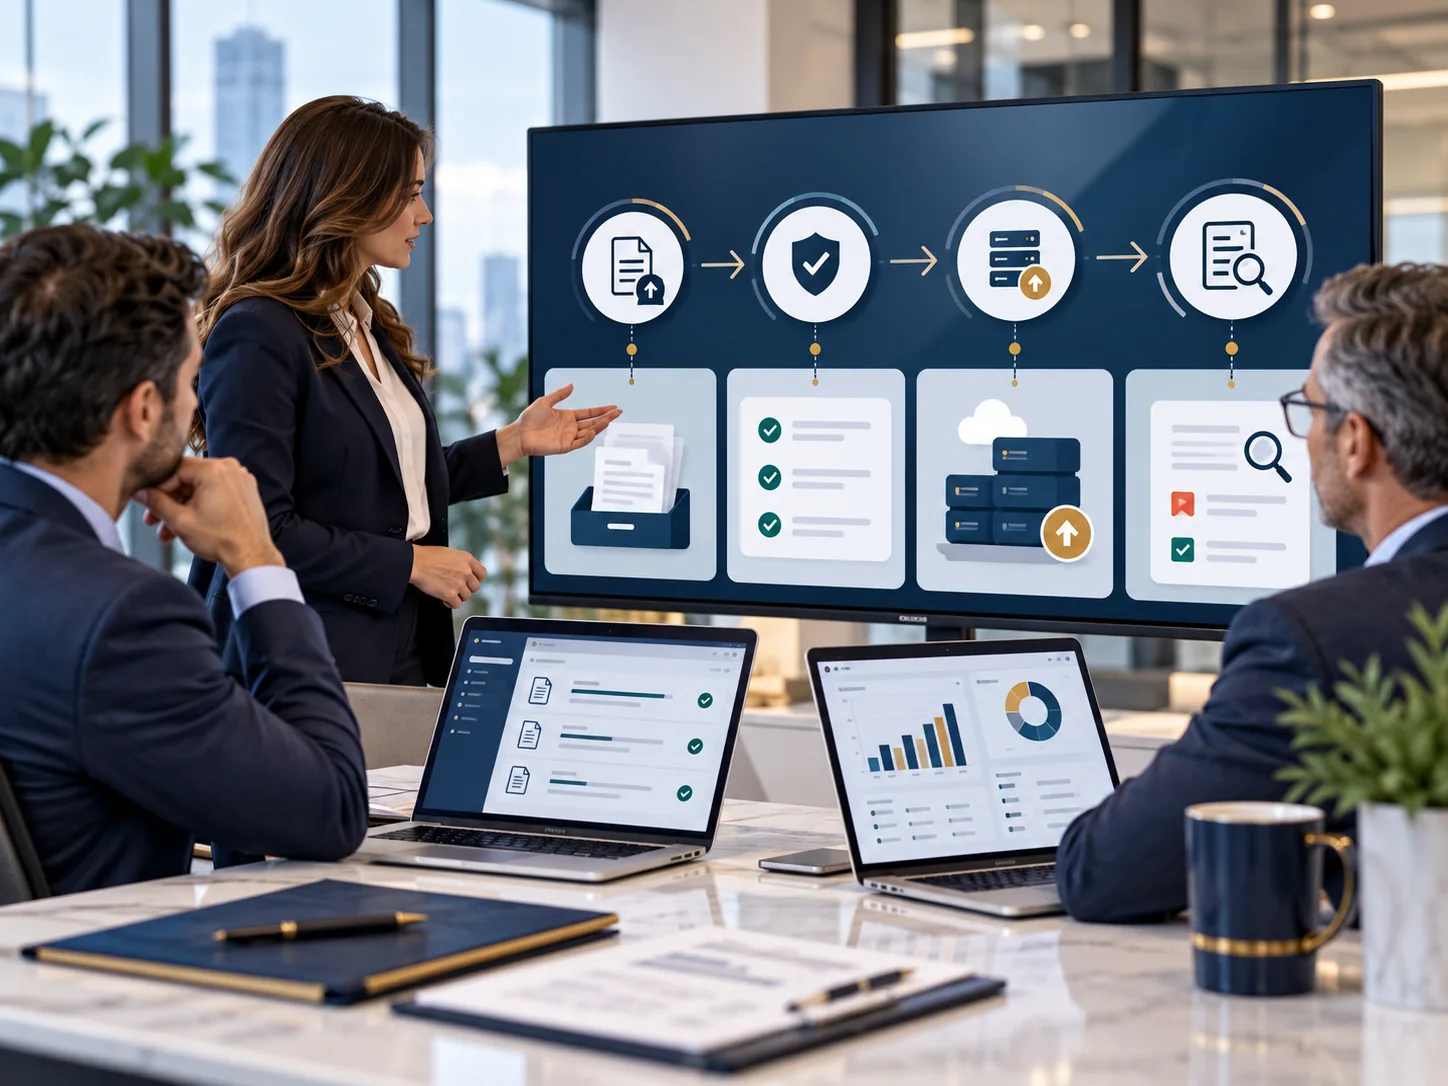
Confirm firm identity, agreement terms, scope and data controls.
Assess bankruptcy chapter, petition dates, legal obligations and bureau rules.
Reconcile ledgers and prepare records under approved Metro 2 mappings.
Manage exception resolution, disputes, corrections and quality reviews.
Prepetition Chapter 7 attorney-fee obligations can be dischargeable. Postpetition agreements and Chapter 13 fee arrangements require separate analysis. A signed payment plan does not automatically make a receivable eligible for credit reporting. Consumer reporting rights and truthful dispute investigation are central to the proposed program.
Interested in helping develop a verifiable, compliant workflow for your firm's eligible fee agreements? Contact BK Aftermath about the proposed program and readiness requirements.
Explore a Partnership →